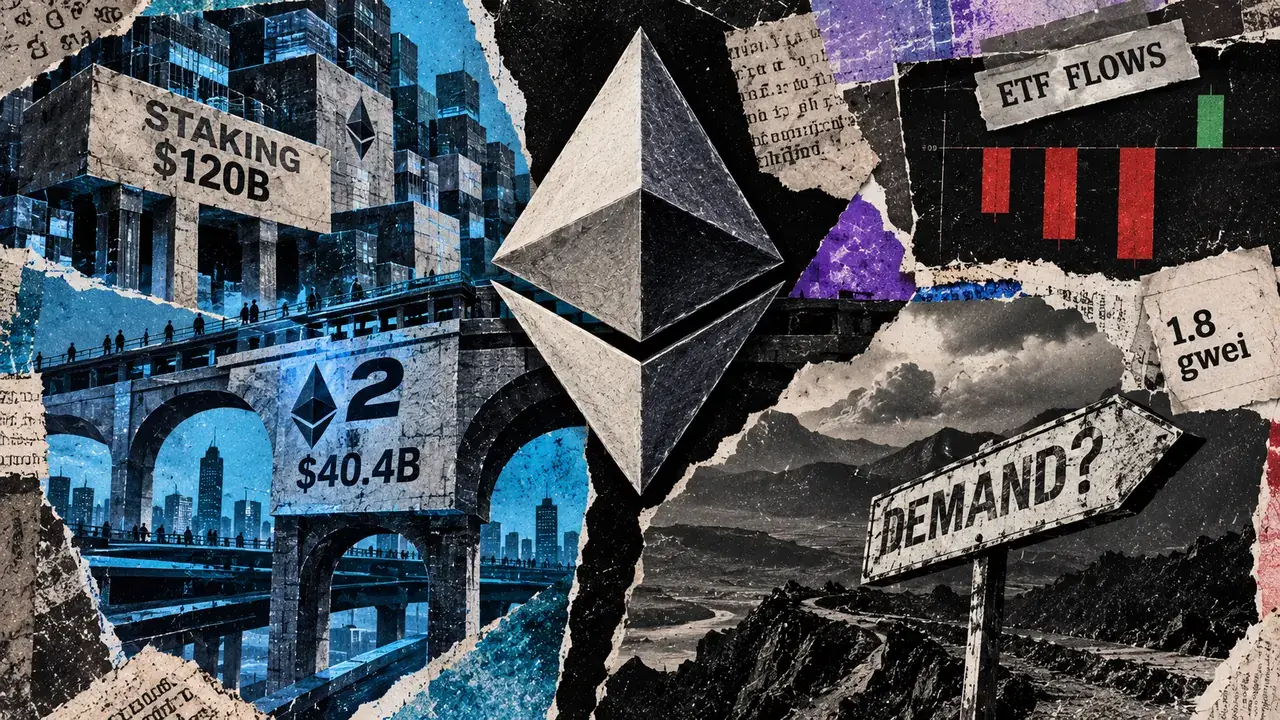
Ethereum’s institutional data hub showed about $120 billion in staked ETH and $40.4 billion in daily average total value locked on layer-2 (L2) networks in a Sept. 21 snapshot.
They measure different things: ETH committed to network security and assets held across L2 networks, so adding them together would not measure fresh ETH demand.
Meanwhile, US-traded Ethereum ETF sessions saw over $140 million in net outflows from Sept. 15 to 18. Large pools of staked ETH and assets on Ethereum-linked networks can coexist with investors pulling money from a particular investment channel.
A staking balance is not a purchase receipt
Staking involves depositing ETH to activate validators, which help secure Ethereum and earn rewards.
An owner can stake ETH already held, resulting in staking participation. Yet, they could also acquire ETH specifically to stake it, so the result is not necessarily fresh demand in all cases.
A staking balance expressed in dollars reflects both the ETH committed and its valuation, so it should not be read as the amount of new capital investors supplied during a particular day or week.
Liquid staking tokens can represent deposited ETH and allow holders to transfer that exposure. The underlying stake remains committed to validation, while the holder may retain a route to liquidity.
For investors, the key question is how much ETH was acquired before being staked. Farside Investors’ Ethereum ETF table provides a dated view of one investment channel.
Last week started with $121.1 million in inflows on Sept. 14, then the funds bled $405.4 million from Sept. 14 to Sept. 17. US-traded spot Ethereum ETFs closed the week on Sept. 18 with $143.7 million in fresh inflows.
ETF flows also cannot settle the question of total ETH demand, as they only describe movements through those funds.
L2 assets and Ethereum fees are different measures
The $40.4 billion L2 figure measures assets on the networks, while the connection to ETH holders runs through what those networks actually pay for Ethereum’s services.
L2BEAT’s on-chain-costs measure tracks operator payments for posting transaction data, proofs, and state updates. Its breakdown includes calldata, blobs, compute, and overhead. Those costs differ from the fees users pay directly to an L2, and blob spending alone does not represent the whole settlement bill.
Even total operator spending is not identical to ETH burned. Ethereum’s execution base fee is burned, while priority fees go to validators. Blob fees operate in a separate market and are also burned.
That distinction prevents a simple leap from rising L2 activity to a proportional benefit for every ETH holder. Assets held, fees charged to users, payments to Ethereum, and supply reduction are separate measurements.
Ultrasound.money displayed 1.8 gwei in its gas header on Sept. 21. Lower execution base fees mean less ETH burned per unit of gas consumed, other things equal. They can also reflect successful scaling that makes transactions cheaper.
Total burn depends on gas consumed and the applicable execution and blob fees, and net supply change also depends on how much ETH is issued.
Staking gives ETH a role in securing the network, while settlement gives it a role in paying for Ethereum’s services.
Whether those uses translate into additional purchases or a shrinking supply depends on acquisition flows and fees over time. The size of the ecosystem is just a starting point for that assessment.
